On this page
The short version
- KYC identity verification is a regulatory obligation for brokers, not a red flag about you.
- Core identity data points are consistent across jurisdictions: name, date of birth, address, and an identification number.
- Enhanced due diligence, such as source-of-funds documents, can apply when risk factors like jurisdiction appear.
- Same-name or closed-loop withdrawals follow the logic of AML rules; processing times and fees are broker policy you can compare.
- Withdrawal fees and account-currency conversion costs are separate cost layers — both belong in your broker comparison.
Before a single trade is placed, every regulated forex broker has to know exactly who is opening the account. That process — identity verification, usually called KYC — is one of the least glamorous parts of trading and one of the most important to understand, because it shapes both your first deposit and, later, how your withdrawals behave. This article explains why brokers ask for documents, what the rules actually require, and where withdrawal friction is normal versus where it should make you pause. All regulation described here is jurisdiction-specific; nothing in this article is universal, and nothing here is financial or legal advice.
Why brokers verify identity at all
Know Your Customer (KYC) refers to the procedures regulated financial businesses use to verify who a customer is and to assess the risks of doing business with them. It sits inside the broader framework of anti-money laundering (AML) and counter-terrorist-financing rules that regulators impose on banks, brokers and increasingly on fintech and other intermediaries [1].
The obligation runs in both directions. For the customer, verification can feel like bureaucracy. For the broker, it is a legal requirement: a regulator will judge the firm on whether it took "actions it can take to counter the risk that they might be used to further financial crime", which is exactly how the UK Financial Conduct Authority frames the purpose of its financial-crime guide (FCG) [2]. The FCA adds that effective systems and controls help firms "detect, prevent and deter financial crime" [2]. In other words, when a broker asks for your passport, it is not doing you a favor — it is satisfying duties it cannot opt out of.
The US version makes the structure explicit. Under section 326 of the USA PATRIOT Act, financial institutions must have a Customer Identification Program (CIP): at minimum, verify the identity of anyone opening an account, keep records of that information, and check it against government watch lists [1].
What verification asks for
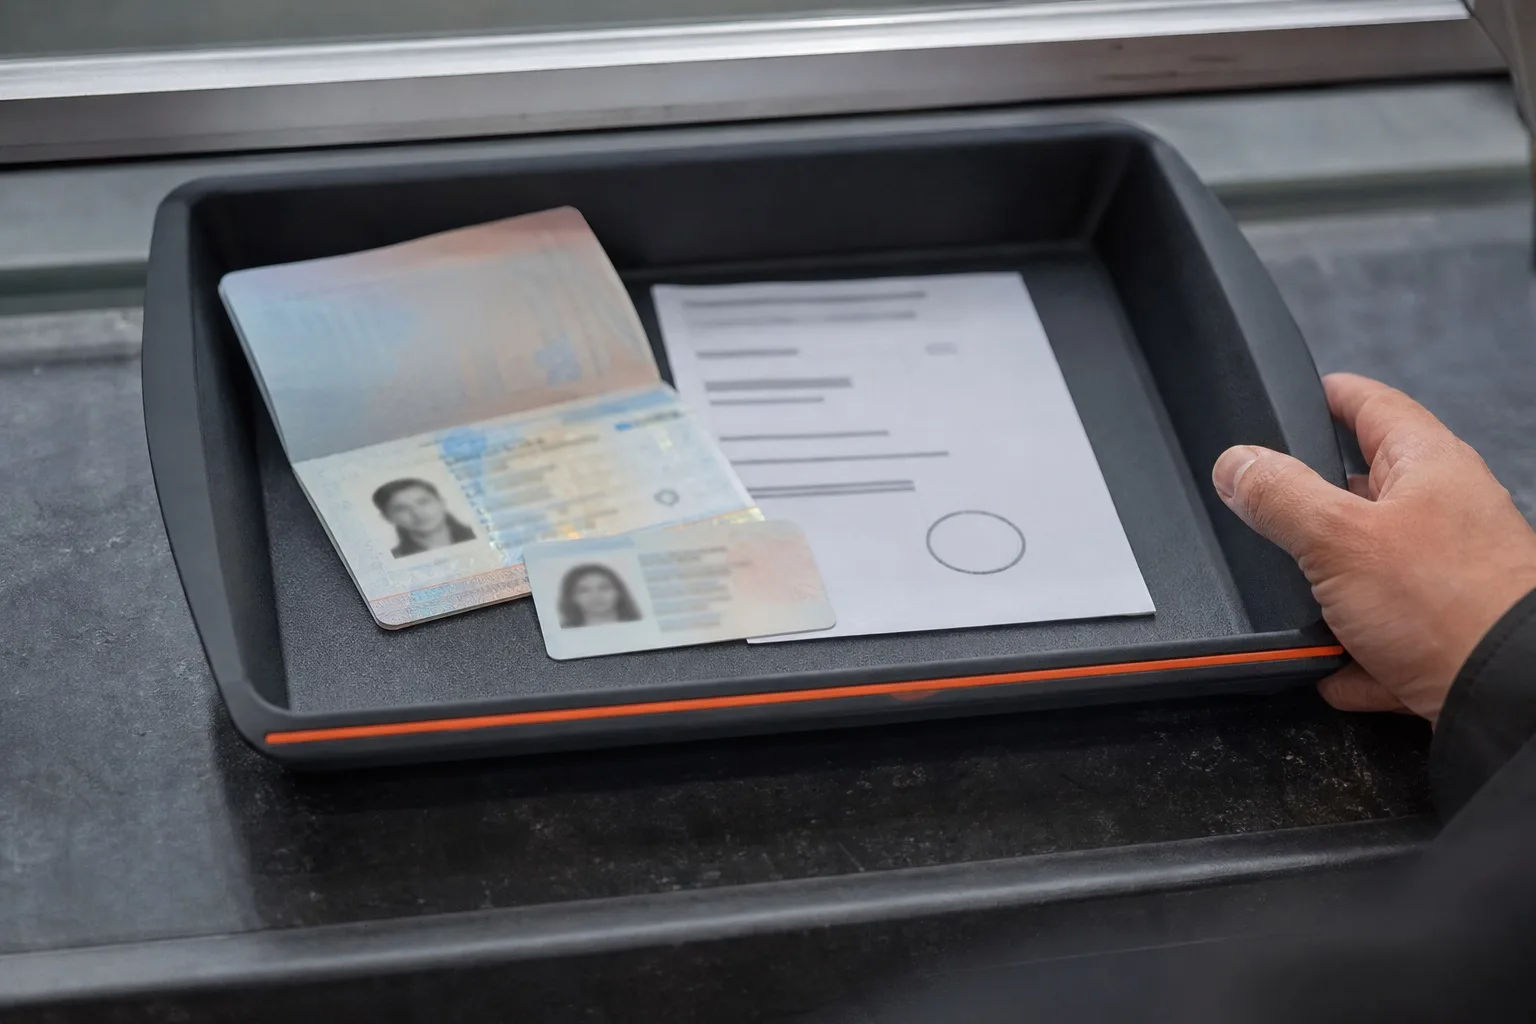
The core data points are remarkably consistent across jurisdictions. The CIP framework requires four pieces of identifying information: name, date of birth, address, and an identification number [1]. For a retail forex trader that typically translates into:
A government-issued photo ID (passport or national ID card).
Proof of address — commonly a utility bill or bank statement, because "address" is one of the required data points.
Payment-side checks: brokers match the account used to deposit with the account holder's name, because accepting third-party funds would undermine the entire identity chain.
Beyond the initial check, Customer Due Diligence (CDD) means understanding the nature of the customer's business and monitoring that transactions stay consistent with what the broker knows about them, including determining whether the customer is a Politically Exposed Person [1]. Enhanced Due Diligence (EDD) kicks in when high-risk factors appear — for example, the customer's jurisdiction — and may require extra documentation such as source-of-funds evidence [1].
The US AML-program rule shows how this scales into ongoing obligations, not one-off paperwork: a written program with internal controls, independent testing, a designated compliance officer, ongoing training, and "appropriate risk-based procedures for conducting ongoing customer due diligence", including monitoring to identify and report suspicious transactions and maintaining and updating customer information [3]. That rule applies to US broker-dealers in securities — it is cited here as an example of how AML programs are structured, not as a rule binding on every forex broker everywhere.
What happens while verification is pending
Until verification completes, most brokers restrict something. Common patterns: deposits are accepted but withdrawals are blocked, or trading is possible on a limited basis. The exact restrictions are broker policy layered on top of regulatory minimums, so they differ firm by firm. Two practical consequences follow:
Do the verification before you plan to trade. An account opened on the weekend may sit in the queue until a human reviews documents; if your first live trade is time-sensitive, an unverified account is a preventable bottleneck.
Treat "pending" as a status, not a verdict. Document rejections are usually procedural — a blurred scan, a proof of address older than the broker's stated window — rather than an accusation.
That said, verification is genuinely risk-based: the same broker may ask one customer for a passport photo and another for source-of-funds documents. Uneven treatment between customers is expected under a risk-based model, not evidence of arbitrariness.
Withdrawal rules: law versus house policy
Withdrawal friction is where traders most often misjudge brokers, because two very different things produce it.
Rules driven by AML logic. The strongest pattern across jurisdictions is the same-name or "closed loop" withdrawal: money goes back to the account it came from, in the same name as the trading account. This is a direct consequence of the identity chain described above — once the broker has verified you, releasing funds to a differently-named account would break that chain. Restrictions on third-party payments are the same principle. Where a broker enforces these strictly, it is usually following the logic of its AML obligations rather than making money harder to reach.
Broker policy and cost recovery. Processing times, cut-off times, and withdrawal fees are largely commercial decisions. They are legitimate points of comparison between brokers, and they are not uniform.
A related but distinct protection is client-money segregation — the arrangement by which a broker keeps customer funds separate from its own operating funds. It matters because it changes what happens if the broker itself fails, and it is a genuinely different safeguard from fast withdrawal processing. A broker can be quick to pay out while holding client money in ways that offer less protection; the two qualities do not travel together, and checking both separately is part of proper due diligence. (The specific rules vary by regulator; this article does not certify any particular broker's arrangements.)
Withdrawal costs: a worked example
Two cost layers are easy to overlook: the broker's withdrawal fee and the currency-conversion cost if your withdrawal account currency differs from your trading account. Consider an illustrative withdrawal of $1,000:
Under a 0.5% withdrawal fee, you would receive $1,000 × (1 − 0.005) = $995.00.
Under a 1.1% total conversion drag (a spread applied across the conversion), you would receive $1,000 × (1 − 0.011) = $989.00.
The difference between the two scenarios is $6.00 per $1,000 withdrawn.
These numbers are illustrative, not observed quotes from any broker. The point is structural: a fee you can see on a fee page and a conversion spread buried in an exchange rate can cost similar amounts, and the second one is easy to miss when choosing an account currency. If you will deposit and withdraw in the same currency, an account denominated in that currency avoids the conversion layer entirely.
Red flags versus legitimate delay
Some delays are explainable: first withdrawals, source-of-funds reviews on large or unusual activity, name mismatches between the payment method and the trading account. None of that makes every delay innocent, though. Warning signs worth weighing include withdrawal terms that changed after you deposited, demands for fees to be paid before a withdrawal is released (a known scam pattern), and verification requests that escalate without explanation. This article cannot tell you whether any specific broker is safe — that judgment needs the broker's own regulatory status, checked against the regulator's register, and the other evidence gathered in a proper review.
A short checklist before depositing
Know which documents your ID type implies: photo ID, recent proof of address, and — if the broker flags risk factors — possibly source-of-funds evidence [1].
Check whether the withdrawal account must match the deposit account, and plan for that in advance.
Compare withdrawal fees and account-currency conversion costs, not just one.
Find the broker's stated processing time and segregation policy in writing, and confirm the broker's authorization on its regulator's public register rather than trusting the website badge.
Verify early. Finishing KYC before you need money moving is the cheapest risk management available.
Verification is not a hurdle placed in front of traders; it is the mechanism that makes the rest of the system accountable. Understanding it, and reading the withdrawal rules before depositing, tells you more about how a broker will behave when you want your money back than almost any marketing claim will.
Sources
[1] Wikipedia, "Know your customer" — CIP data points and USA PATRIOT Act §326, CDD/EDD definitions. https://en.wikipedia.org/wiki/Know_your_customer (retrieved 2026-10-21) [2] FCA Handbook, Financial Crime Guide (FCG) 1 — purpose and framing of financial-crime systems and controls. https://www.handbook.fca.org.uk/handbook/FCG/1/?view=chapter (retrieved 2026-10-21) [3] eCFR, 31 CFR § 1023.210 — AML program requirements for brokers or dealers in securities (US broker-dealers; cited as a structural example). https://www.ecfr.gov/current/title-31/subtitle-B/chapter-X/part-1023/subpart-C/section-1023.210 (retrieved 2026-10-21)
Sources & further reading
Check the original source for its scope, publication date and latest terms.
- Wikipedia — Know your customerhttps://en.wikipedia.org/wiki/Know_your_customer
- FCA Handbook — Financial Crime Guide (FCG) 1https://www.handbook.fca.org.uk/handbook/FCG/1/?view=chapter
- eCFR — 31 CFR § 1023.210 (AML program requirements, US broker-dealers)https://www.ecfr.gov/current/title-31/subtitle-B/chapter-X/part-1023/subpart-C/section-1023.210
For education and research, not personal investment advice. Trading involves risk. Broker terms and protections depend on your country, account and contracting legal entity.